When the Number Comes In Low: A Buyer's and Seller's Guide to Surviving the Appraisal Gap
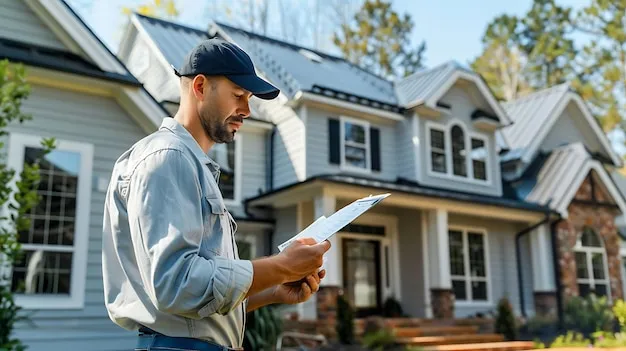
Photo: house appraisal inspector reviewing documents outside home, via img.freepik.com
You found the house. You negotiated in good faith. Your offer was accepted, inspections went smoothly, and closing was circled on the calendar. Then the appraisal report landed in your lender's portal, and the number staring back at you was $15,000 below what you agreed to pay.
Welcome to the appraisal gap — one of the most common and least understood hurdles in American home buying. It is not a reason to panic, but it is a reason to slow down and think strategically. This guide explains why gaps happen, what your lender is actually doing, and the four realistic paths forward, complete with dollar figures and language you can use when the conversation gets tense.
Why Appraisals Come In Low
An appraisal exists to protect the lender, not the buyer. Before a bank lends you $340,000 on a $350,000 house, it wants independent confirmation that the property could be sold to recover its money if you defaulted. The appraiser's primary tool is the comparable sale — recently closed transactions of similar homes nearby.
Low appraisals cluster in a few predictable situations:
- Fast-moving markets. When prices rise quickly, closed sales lag behind what buyers are currently willing to pay. A contract signed in March may reflect conditions the appraiser cannot document with sales from the previous quarter.
- Thin inventory of comps. In rural areas, older subdivisions, or neighborhoods with few transactions, the appraiser may be forced to use sales that are months old or several miles away.
- Unusual properties. A home with a converted garage apartment, an oversized lot, or a distinctive floor plan resists easy comparison.
- Emotional bidding. In multiple-offer situations, buyers sometimes bid $20,000 over list on pure momentum. Appraisers, bound by data rather than enthusiasm, often don't.
Consider a realistic example: a buyer contracts at $425,000 on a home listed at $399,000 after a bidding war. The appraiser finds three comparable sales at $402,000, $408,000, and $411,000, and arrives at an opinion of value of $407,000. The gap: $18,000.
Path One: Renegotiate the Price
The most common resolution is also the simplest. The buyer returns to the seller and says, in effect: the bank won't lend more than the home is worth, so the price should reflect that.
Sellers resist this — nobody enjoys lowering a price after celebrating an offer — but they often have little choice. If the buyer's financing is contingent on appraisal and the buyer is well-qualified, the alternatives are usually worse for the seller: put the house back on the market, disclose the low appraisal to future buyers, and explain a price reduction anyway.
A useful script for the buyer's agent:
"My clients remain committed to the purchase. The appraisal came in at $407,000, and their lender will not exceed that figure. They're prepared to move forward at that number, or we can split the difference at $416,000 if the sellers can meet us partway. We'd like to close on the original date either way."
Splitting the gap is common. In our example, a seller who concedes $10,000 of an $18,000 shortfall keeps the deal alive while the buyer absorbs the rest.
Path Two: Pay the Difference in Cash
If the buyer loves the property and has the liquidity, the gap can simply be paid. This changes the math of the transaction in a way worth understanding.
Using the same numbers: the buyer is borrowing 90 percent of $407,000 — $366,300 — with a $40,700 down payment plus $18,000 to cover the gap. Total cash to close rises by $18,000, and because the loan no longer matches the original ratio, the buyer should confirm with the lender whether the change affects rate pricing or mortgage insurance.
Before choosing this path, ask a blunt question: is the home worth $18,000 more than the appraiser's number to you? If the buyer plans to stay ten years and the premium buys a better location or layout, paying it may be rational. If the buyer is stretching to win a bidding war, it may be the first step toward being underwater.
Path Three: Dispute the Appraisal
Appraisals can be challenged, and they are sometimes revised. The buyer may request a Reconsideration of Value, supplying evidence the original report missed:
- Closed sales that occurred after the appraisal's effective date
- Comparable properties the appraiser overlooked, perhaps a better-matched sale in an adjacent subdivision
- Factual errors — an incorrect square footage, a missed finished basement, an extra half-bath
The lender submits the package to the appraiser, who may adjust the value, order a second appraisal, or hold firm. Success rates vary, but a well-documented challenge built on genuine closed comps — not on the buyer's opinion that the house is lovely — has a real chance.
Path Four: Walk Away, Deliberately
Every purchase contract with an appraisal contingency includes an exit. If renegotiation fails, the buyer will not or cannot cover the difference, and the challenge is denied, the buyer can typically terminate and recover earnest money. It stings, but it is the contingency doing exactly what it was designed to do.
Sellers should hear this plainly: a buyer walking on appraisal is not a betrayal. It is the market delivering a data-backed message about price.
Preventing the Gap Before It Forms
Buyers can reduce exposure by reviewing recent comparable sales with their agent before submitting an offer, and by capping escalation clauses at figures supported by those comps. Sellers can pre-empt the problem by preparing an appraiser packet — a list of upgrades with costs, permits for improvements, and any relevant sales the seller believes support the price.
An appraisal gap is not a dead end. It is a negotiation with a number attached — and handled calmly, with the right guidance, it is a problem with four solutions, not zero.