Earning Their Keep: Nine Upgrades That Shrink Your Monthly Housing Costs, Not Just Your Electric Bill
Photo: The Government-General of French Indo-China., Public domain, via Wikimedia Commons
There is a familiar ritual in American home improvement: the homeowner spends $18,000 on new windows, then spends the next decade telling anyone who will listen that the project 'pays for itself' in energy savings. Sometimes it does. More often, the math is softer than the sales pitch.
But a quieter conversation is happening among financially minded buyers and owners — one that has less to do with kilowatt-hours and more to do with the full monthly carrying cost of a home. Insurance premiums, property tax assessments, mortgage terms, and rental income all move when you change what a house is. Below are nine renovations that can genuinely reduce what you pay each month, with realistic payback horizons.
1. The Energy Audit Before Anything Else
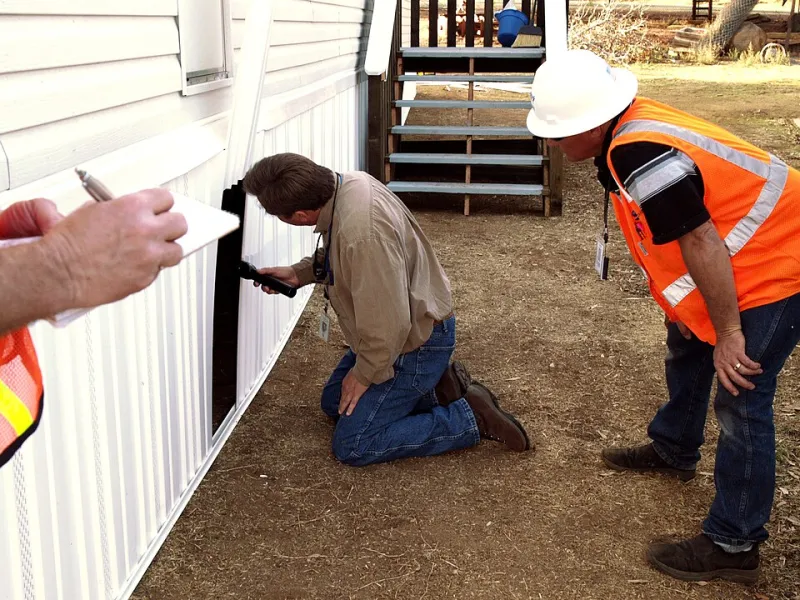
Before swinging a hammer, spend $200–$500 on a professional home energy audit, often subsidized by utility companies. It identifies where your house actually leaks money — frequently in attics and rim joists rather than the windows everyone blames. Air sealing and added insulation typically cost $2,000–$4,000 and can trim heating and cooling bills 15–20 percent, with payback in two to five years. The federal Energy Efficient Home Improvement Credit covers 30 percent of qualifying costs up to $1,200 annually.
2. Heat Pumps: The Inflation Reduction Act's Favorite Child
Replacing an aging furnace or air conditioner with a heat pump qualifies for a credit of up to $2,000 under current federal incentives, and many state programs and utilities layer on rebates. In moderate climates — the Carolinas, the Pacific Northwest, much of the Mid-Atlantic — a heat pump can cut heating and cooling costs 30 to 50 percent compared with resistance heating or older systems. Payback periods run five to ten years, faster if you are replacing equipment at end of life anyway.
3. Roofing That Insurers Reward
Here is a renovation with a direct line to your monthly budget: an impact-resistant or newer roof can reduce your homeowners insurance premium by 5 to 25 percent in many states. In hail-prone Colorado or Texas, insurers increasingly offer meaningful discounts for Class 4 impact-rated shingles, and in wildfire-exposed California, hardened vents and defensible-space landscaping can be the difference between getting coverage at all. Given that premiums in some markets now exceed $400 a month, a roof that shaves 15 percent off is doing real work.
4. Solar With a Sober Eye
Solar photovoltaic systems deserve neither the hype nor the scorn they receive. A typical 8-kilowatt system costs $20,000–$25,000 before the 30 percent federal tax credit. In high-rate markets like California, Massachusetts, and Hawaii, monthly savings can exceed the financing payment from day one. In low-rate states like Louisiana or North Dakota, payback can stretch past 15 years. The rule of thumb: solar pays best where utility rates are high and net metering is generous.
5. The Accessory Dwelling Unit
No renovation lowers net housing costs faster than adding a rentable unit. A detached ADU in California might cost $150,000–$300,000, but a garage conversion in Denver or a basement apartment in Portland can run $50,000–$100,000 and command $1,200–$2,000 in monthly rent. A homeowner paying $2,400 monthly on a mortgage who collects $1,400 from a basement suite has effectively cut their housing cost by more than half. Check local zoning first — many cities have relaxed ADU rules dramatically since 2020, but HOA covenants can still block you.
6. House Hacking by Another Name: The Finished In-Law Suite
Short of a full ADU, converting a spare bedroom suite for a long-term housemate or a furnished rental can generate $600–$1,000 monthly in many metros. It is the least glamorous item on this list and often the highest-return.
7. Tax-Smart Medical and Accessibility Modifications
For households with aging members, certain accessibility renovations — ramps, walk-in tubs, widened doorways — may be deductible as medical expenses if they exceed the standard threshold and are prescribed for care. More broadly, these modifications can delay or avoid the enormous cost of assisted living, which now averages over $5,000 monthly nationally. The renovation is not the point; the avoided expense is.
8. Water Management in Flood Zones
If your property sits in or near a FEMA flood zone, elevation certificates, improved drainage, flood vents, or raising mechanicals can cut flood insurance premiums dramatically — sometimes by thousands of dollars per year. In coastal Louisiana and New Jersey, a compliant elevation certificate alone has saved owners $2,000 or more annually. This is among the most overlooked line items in the entire renovation calculus.
9. The Mortgage Refinance Trigger
Not a renovation, but a consequence of one: substantial appraised-value increases from major improvements can unlock better loan-to-value ratios, eliminating private mortgage insurance. Dropping PMI typically saves $30–$70 per month per $100,000 borrowed. On a $400,000 loan, that is real money for a project you may have wanted anyway.
A Note on Sequencing
The through-line in all nine is that the monthly payment — insurance, taxes, utilities, loan terms, offsetting income — matters more than the sticker price of the project. Buyers evaluating a home should ask sellers for utility histories and insurance claims records; owners should run each candidate project through the same filter: what does this change about my monthly number, and when does it break even?
A house that merely looks improved is a cost. A house engineered to pay you back every month is an asset. The difference is almost always in the planning, not the paint.